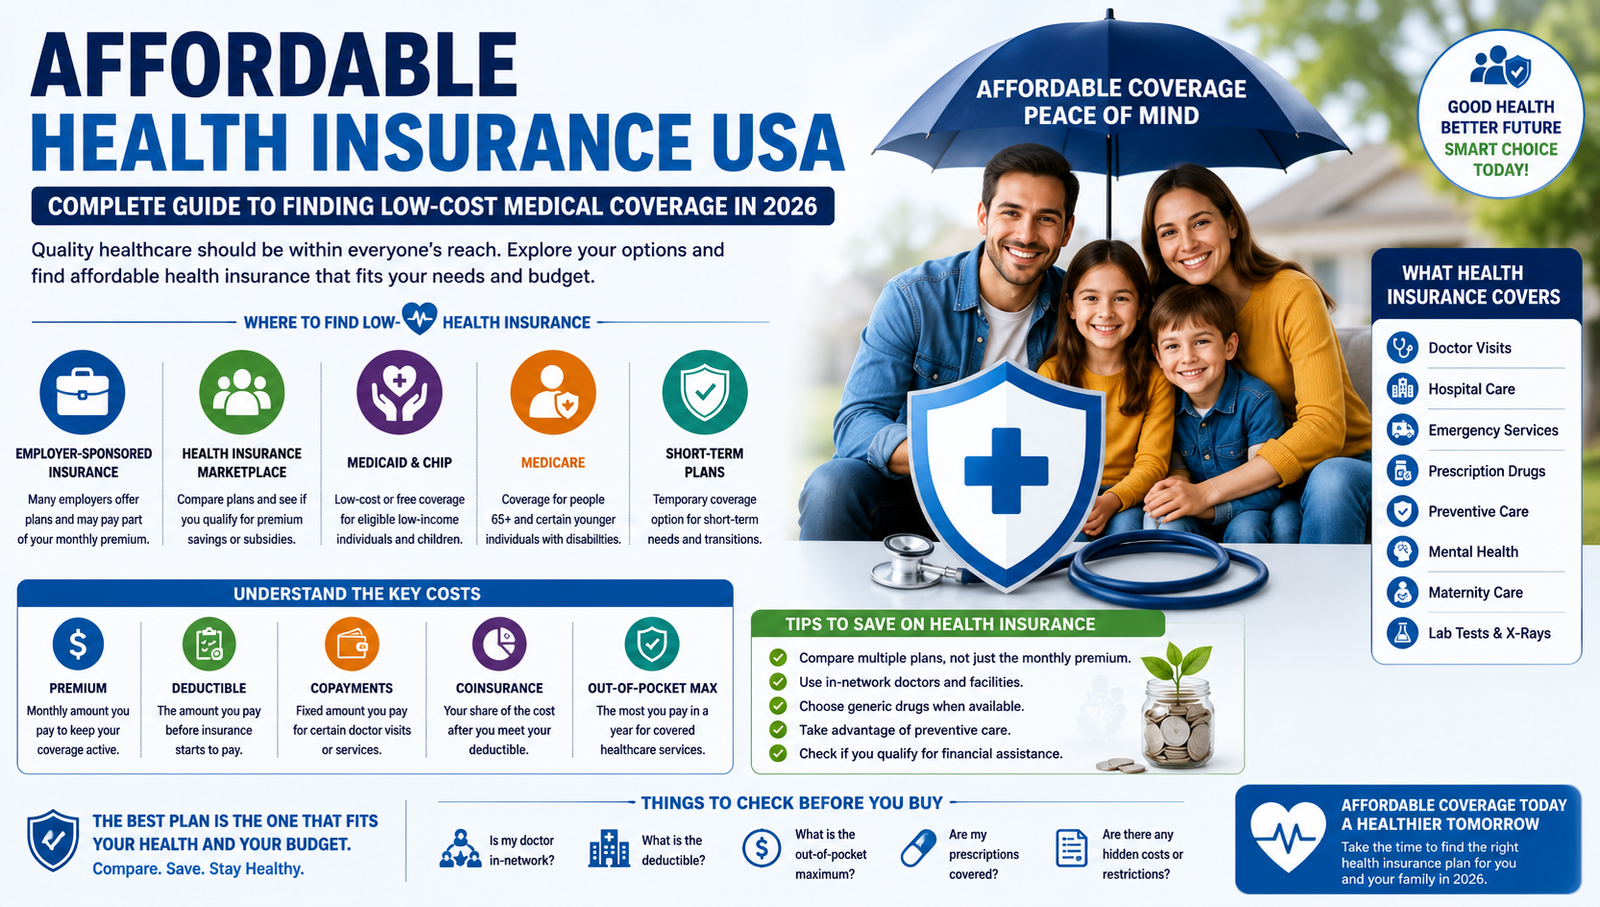
Finding affordable health insurance in the United States can be challenging, especially when you are trying to balance monthly premiums, deductibles, copayments, and unexpected medical expenses. The good news is that several options may help individuals and families find lower-cost health coverage in 2026.
Affordable health insurance does not always mean choosing the plan with the lowest monthly premium. A plan with a very low premium may have a high deductible or limited provider network. The best option is usually a plan that provides a reasonable balance between monthly costs, healthcare benefits, provider access, and protection from large medical bills.
This guide explains how health insurance works, where to find affordable coverage, what costs to compare, and how to choose a plan that fits your needs.
What Is Affordable Health Insurance?
Affordable health insurance is coverage that provides access to necessary medical services without placing an excessive financial burden on the policyholder.
Depending on your circumstances, affordable coverage may come through an employer, the Health Insurance Marketplace, Medicaid, Medicare, or another qualifying program.
Health insurance generally helps pay for services such as doctor visits, preventive care, hospital treatment, emergency services, prescription drugs, and specialist care. The exact benefits depend on the policy.
When comparing plans, it is important to consider both what you pay for coverage and how much you may have to pay when you actually use healthcare services.
Where Can You Find Low-Cost Health Insurance in the USA?
1. Employer-Sponsored Health Insurance
For many Americans, employer-sponsored health insurance is one of the most affordable options.
Employers may pay part of the monthly premium, reducing the amount employees have to contribute. Some employers also offer multiple plans with different deductibles, networks, and benefit levels.
Before choosing an employer plan, compare the employee premium, deductible, out-of-pocket maximum, prescription coverage, and provider network.
2. Health Insurance Marketplace Plans
People who do not receive affordable employer coverage may be able to purchase an individual or family plan through the federal or state Health Insurance Marketplace.
Marketplace plans are organized into metal categories such as Bronze, Silver, Gold, and Platinum. These categories generally indicate how healthcare costs are divided between the insurer and the member rather than the quality of medical care.
Depending on household income and eligibility, some consumers may qualify for premium assistance or other savings.
3. Medicaid and CHIP
Medicaid provides health coverage to eligible low-income individuals and families, while the Children’s Health Insurance Program, or CHIP, provides coverage for eligible children in qualifying households.
Eligibility rules vary by state and can depend on income, household size, age, disability status, pregnancy, and other factors.
For people who qualify, these programs can provide significantly lower-cost coverage than purchasing a private health insurance plan.
4. Medicare
Medicare primarily serves people age 65 and older and certain younger people who meet specific eligibility requirements.
Medicare beneficiaries can choose among different coverage arrangements, including Original Medicare and Medicare Advantage plans. Additional coverage may also be available for prescription drugs and other healthcare expenses.
Because Medicare has different premiums, deductibles, networks, and coverage rules, beneficiaries should compare their options carefully.
Understanding Health Insurance Costs
The cheapest monthly premium is not necessarily the cheapest overall plan. Several costs should be considered.
Monthly Premium
The premium is the amount you pay to keep your insurance active. A lower premium can make a plan easier to afford every month, but it may come with higher costs when you receive medical care.
Deductible
A deductible is the amount you generally pay for covered healthcare services before the plan begins paying according to its cost-sharing structure.
High-deductible plans can have lower premiums, while plans with lower deductibles may cost more each month.
Copayments
A copayment, or copay, is a fixed amount you pay for certain covered services. For example, a plan may charge a set amount for a primary-care visit or prescription.
Coinsurance
Coinsurance is the percentage of the allowed cost of a covered service that you pay after meeting applicable deductible requirements.
Out-of-Pocket Maximum
The out-of-pocket maximum is particularly important when comparing plans. It represents the maximum amount you generally pay during a plan year for covered services subject to the plan’s rules.
A lower out-of-pocket maximum can provide greater protection if you experience a serious illness, accident, hospitalization, or other expensive medical event.
How to Find the Cheapest Health Insurance That Still Provides Good Coverage
Start by determining how much healthcare you expect to use.
If you rarely visit doctors and mainly want protection against unexpected medical expenses, a plan with a lower premium and higher deductible may be worth considering.
If you regularly visit doctors, use prescription medications, see specialists, or expect medical procedures, paying more for a plan with lower cost-sharing may provide better overall value.
Next, check the provider network. A plan may appear inexpensive but become costly if your preferred doctors or hospitals are outside the network.
You should also review prescription coverage. Check whether your medications are included in the plan’s formulary and what cost-sharing requirements apply.
Bronze, Silver, Gold, or Platinum: Which Is Best?
Marketplace plans commonly use four metal categories.
Bronze plans generally have lower monthly premiums but higher costs when you receive care.
Silver plans offer a middle ground between premiums and cost-sharing and may be particularly important for people who qualify for additional cost-sharing assistance.
Gold plans typically have higher premiums but lower costs when healthcare services are used.
Platinum plans generally have the highest premiums and lower cost-sharing for covered services.
There is no universally best category. The right choice depends on your expected healthcare use and financial situation.
Tips for Saving Money on Health Insurance
There are several ways to keep healthcare costs under control.
First, compare multiple plans instead of selecting the first option you see. Look at the total potential annual cost, not just the monthly premium.
Second, use in-network doctors and hospitals whenever possible. Out-of-network care can cost considerably more depending on your plan.
Third, take advantage of covered preventive services when available. Preventive care can help identify health problems early and may reduce future healthcare expenses.
Fourth, review prescription costs. Generic medications may cost less than brand-name alternatives when medically appropriate, and different plans can have significantly different drug coverage.
Finally, check whether you qualify for financial assistance through your employer, Marketplace coverage, Medicaid, CHIP, or other programs.
What to Check Before Buying a Plan
Before enrolling, ask these questions:
- What is the monthly premium?
- What is the annual deductible?
- What is the out-of-pocket maximum?
- Are my doctors in network?
- Are my preferred hospitals covered?
- Are my prescriptions included?
- What are the specialist visit costs?
- Does the plan require referrals?
- How does emergency care work?
- What services require prior authorization?
- Am I eligible for financial assistance?
- Are there separate deductibles for prescriptions or specific services?
Reading the plan’s official Summary of Benefits and Coverage can make comparison easier.
Final Thoughts
Affordable health insurance in the USA in 2026 is about more than finding the lowest monthly premium. A truly affordable plan should provide meaningful protection while keeping both predictable and unexpected healthcare expenses manageable.
Employer-sponsored coverage, Marketplace plans, Medicaid, CHIP, and Medicare can all provide potential options depending on your eligibility and circumstances.
Before choosing a plan, compare premiums, deductibles, copayments, coinsurance, out-of-pocket maximums, provider networks, and prescription coverage. Also check whether you qualify for financial assistance.
The best health insurance plan is ultimately the one that fits your healthcare needs, budget, preferred providers, and expected medical expenses. Taking time to compare your options can help you find reliable coverage without paying more than necessary.